A backtester built to disappoint you honestly
Most backtesters are optimism machines. QuantumCat’s is engineered to make the sim agree with the live bot — the same condition evaluator, the same decision clock, the same risk rails:
- Closed candles, live wake times. Signals evaluate on completed bars; daily-class strategies decide at 09:16 of the next session — the instant the live bot actually wakes — not at a fantasy 15:30 fill on the signal bar. A still-forming last candle is dropped, never traded.
- Stops first, inside every bar. Intrabar resolution assumes the adverse path (stop before target when both are inside one bar). With the tick archive enabled, fills resolve against your recorded real ticks instead of bar assumptions.
- Charges are real. Every simulated trade pays estimated Indian costs — brokerage, STT/CTT, exchange charges, GST, stamp — segment-aware. Net means net.
- Option strategies price honestly: single legs and structures priced with Black-76 at live-inverted IV, theta bleeding daily, expiry settling to intrinsic — never “the index moved 100 points so you made 100 points”.
- Refusal over fantasy. A strategy depending on data the sim can’t reproduce (live spread, unknown history) refuses to run with the reason, instead of returning a confident wrong number.
Market replay
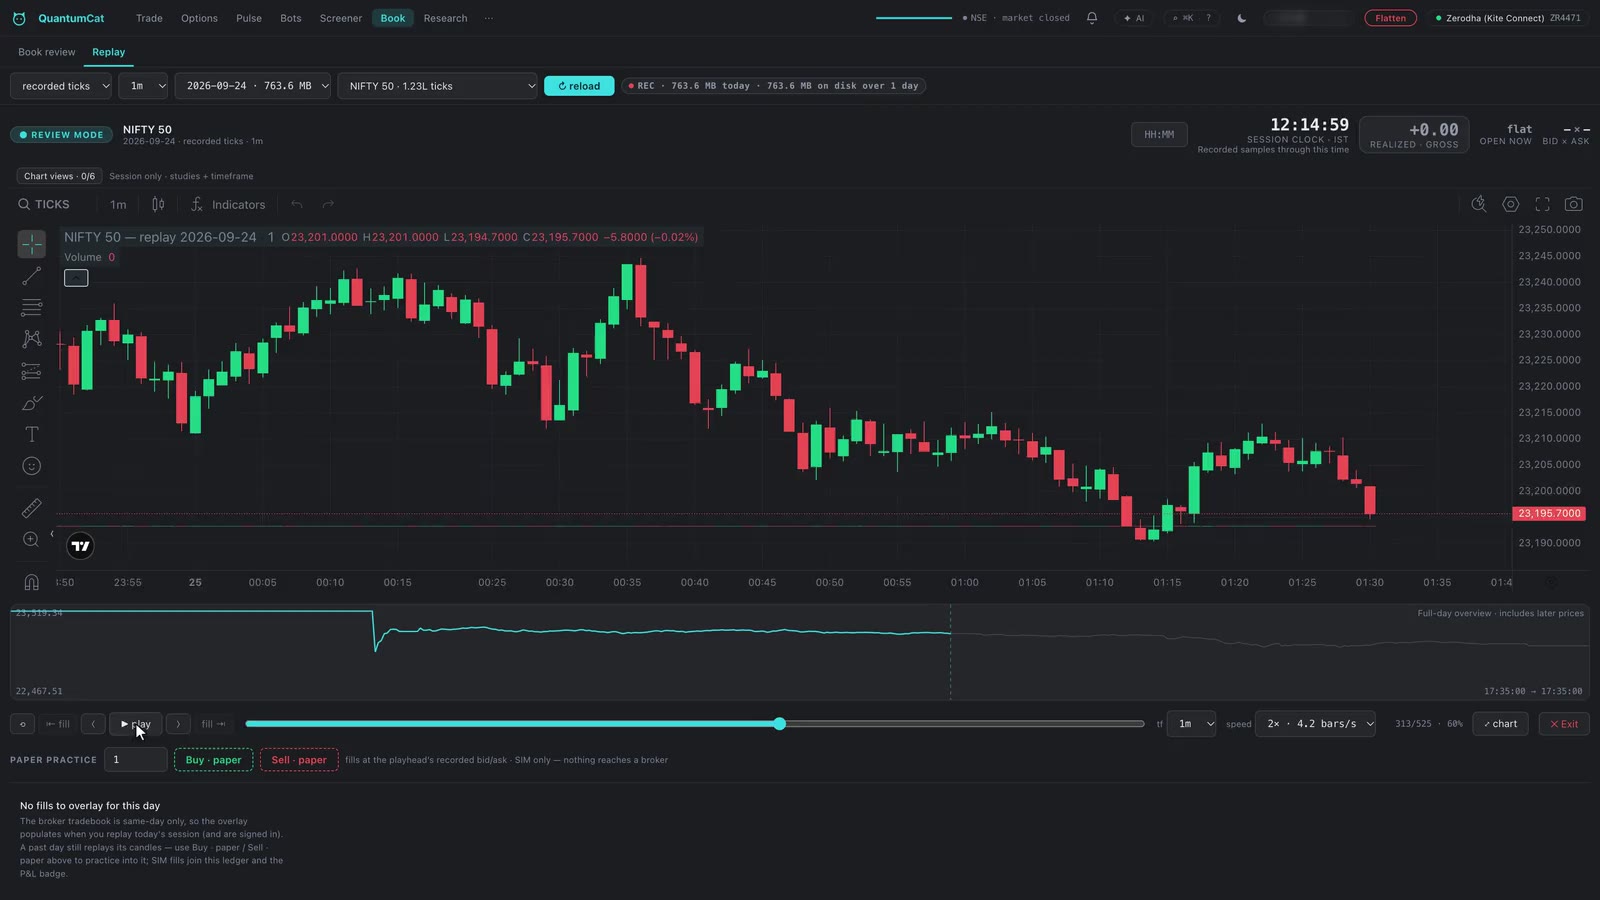
The terminal quietly records your subscribed tick stream (price, volume, depth) into a local archive. Replay any recorded day tick by tick — charts, tape and chain move exactly as they did live — pause, scrub, jump to a timestamp. Rehearse the open, revisit the trade that hurt, or hand a moment to JARVIS (“show me 11:42 on expiry day”) and it deep-links the replay there. The same archive warms your seconds-charts on a fresh launch and powers tick-verified backtest fills.
The self-audit stack
| Instrument | What it answers |
|---|---|
| Trade X-ray | Every closed round-trip replayed against your own recorded tape: your entry and exit beside the exit your own stop/target would have taken, and the rupee gap between them — plus modeled positive-pair percentages, estimated net and expectancy by hour, weekday, instrument class, symbol, recorded pairs per day and the period after a modeled loss. Every bucket is sample-gated; opening positions and full capture remain unverified, so these are not actual account-performance measurements. |
| Ghost compare | A paper replay of recorded fill pairs against a saved stop/target on recorded tape. Differences compare models; they do not establish the cost of a decision or achievable alternate profit. |
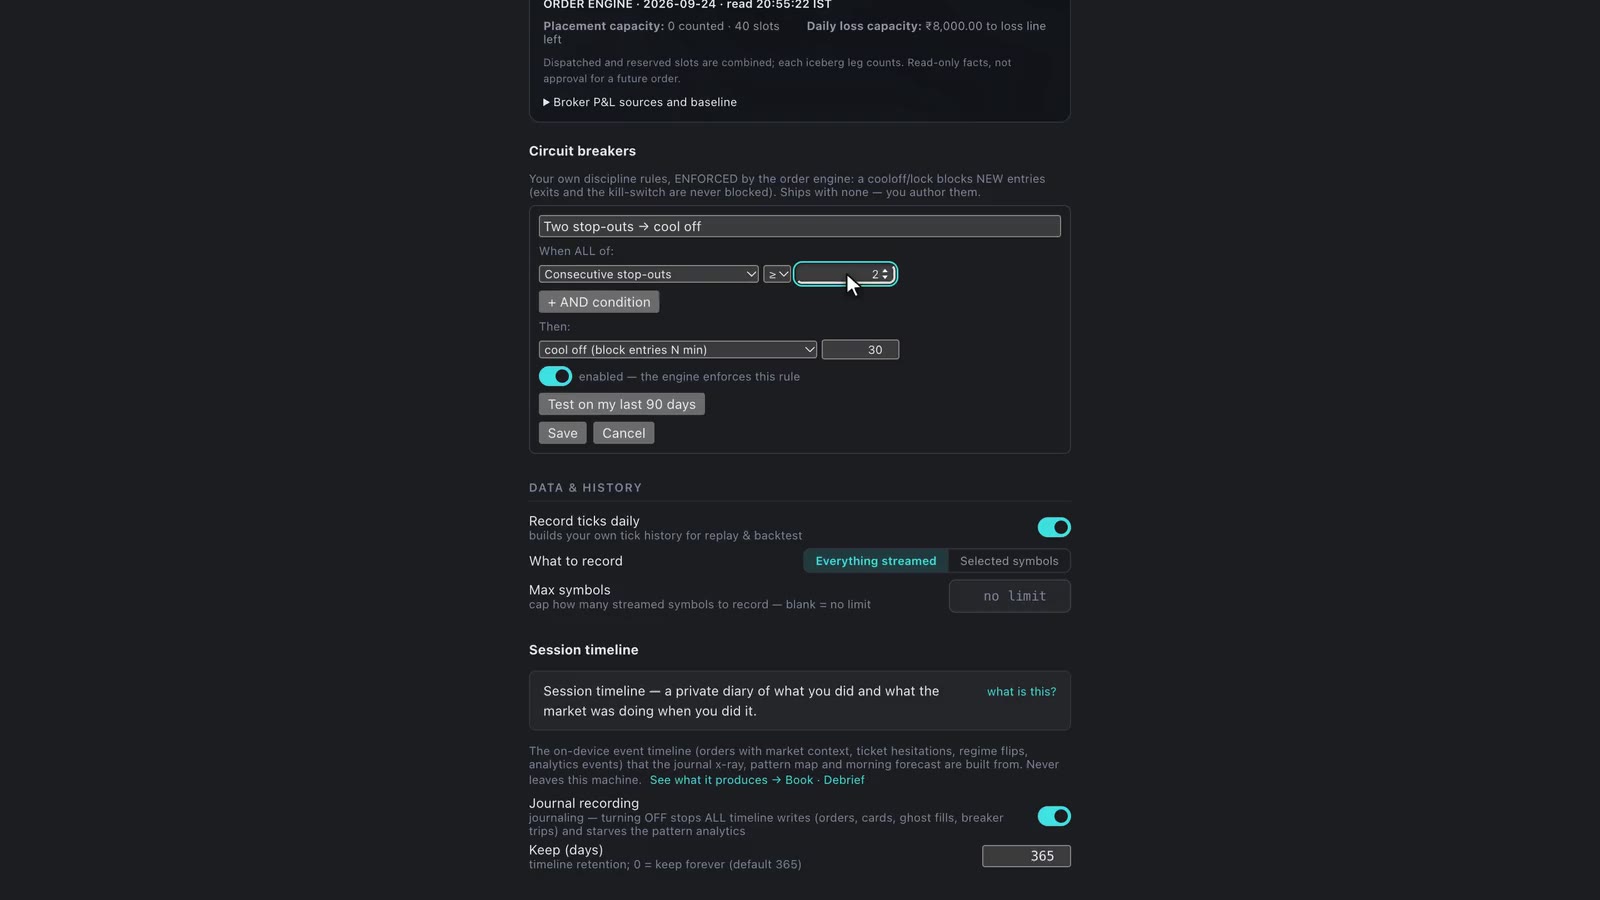
| Discipline breakers | Self-authored circuit breakers (loss streaks, overtrading pace, revenge patterns) enforced in the shared engine — a cooloff blocks fresh entries at the same gate every order passes, with the counterfactual shown. |
| Event spine | An append-only local journal of everything the terminal saw and did — orders, regime flips, signals — queryable by time, feeding the day-classification and pattern analytics. |
| Day P&L history | Per-day realized gross round-trip P&L built from your own fill history, per broker — the broker API only shows today; the terminal remembers. Charges are not deducted there (the Journal tab carries the exact per-trade statutory stack), and a day the app never ran is shown as missing, never as flat. |